
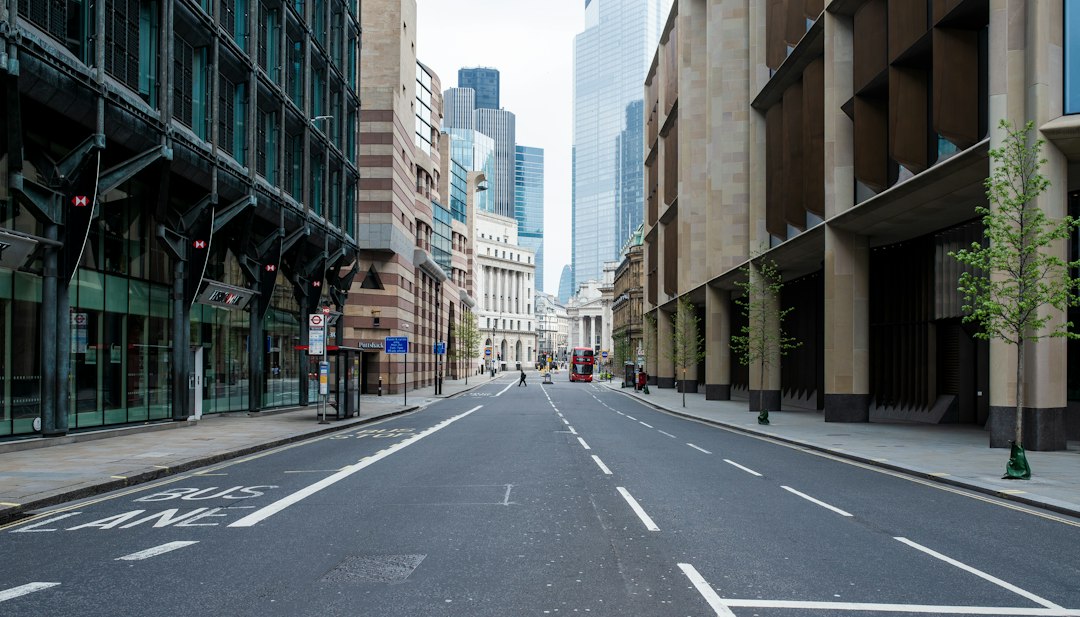
The Financial Conduct Authority has gone back out onto London’s streets. On 10 September 2026, working alongside the Metropolitan Police Service and HM Revenue & Customs, the regulator targeted three premises across London suspected of running illegal peer-to-peer crypto trading operations. Cease and desist letters were issued at all three, ordering the traders to stop.
The action — confirmed in an FCA press release first published on 17 September 2026 and updated as recently as 1 October — is the second coordinated sweep against this exact corner of the crypto market this year, following an earlier operation in April that hit eight London locations. Evidence gathered in that first raid is reportedly still feeding live criminal investigations.
What “peer-to-peer” trading actually means
Peer-to-peer (P2P) trading is simply two individuals buying and selling crypto directly with each other, cash for coin, outside an exchange’s order book — the kind of deal struck in a café, a car park or over a messaging app. Doing it as a business in the UK requires FCA registration under the Money Laundering Regulations. According to the FCA’s own notice, a handful of registered firms carry out some P2P activity as part of a wider, already-registered business — but as things stand, there are currently no solely FCA-registered peer-to-peer crypto trading businesses operating anywhere in the UK. Anyone running one, by definition, is doing it illegally.
That matters because P2P trading sits outside the checks that are supposed to catch dirty money. The FCA is blunt about why it keeps coming back to this: “Unregistered peer-to-peer crypto traders operating by way of business in the UK can provide a route for criminals to move and launder illicit funds. By operating outside the FCA’s registration regime, they avoid controls designed to detect and prevent money laundering.”
“Assume we are looking at them”
Steve Smart, the FCA’s executive director of enforcement and market oversight, didn’t dress up the message for anyone still running one of these operations: “Working with partners, we continue to track and disrupt illegal crypto activity. Anyone running an unregistered peer-to-peer crypto business should assume we are looking at them.”
Detective Sergeant Sathish Alalasundaram of the Met Police described the practical difficulty behind the headline: “The complex nature of cryptocurrency, combined with the speed at which funds can be moved across jurisdictions, presents ongoing challenges for those investigating. As criminals continue to adapt their methods, the Met Police continues to evolve and adapt our investigative capabilities and disruption tactics to bring those who break the law to justice.”
Part of a longer pattern
This is not a one-off. The FCA has been steadily squeezing the UK’s informal, cash-based crypto trade for several years, and the numbers tell their own story:
- In 2023 alone, the FCA inspected 34 locations suspected of hosting crypto ATMs and disrupted 26 machines operating unlawfully.
- London operator Olumide Osunkoya was charged over a £2.6 million illegal crypto ATM network — money laundering offences, forgery, and possessing criminal property under the Proceeds of Crime Act 2002 — and the FCA’s own case notes list him as sentenced to four years.
- Industry tracking firm GENERAL BYTES puts the UK’s legal crypto ATM count at zero, down from roughly 80 active machines in 2022 — a complete wipeout of the physical cash-to-crypto sector through enforcement rather than a change in the law.
- The April 2026 sweep hit eight London premises; this September’s follow-up hit three more, with the FCA saying evidence from the first is actively supporting ongoing prosecutions.
Seen together, it looks less like isolated raids and more like a standing operation that simply keeps returning to the same ground.
Why this is happening now — and what’s still to come
Crypto remains largely unregulated in the UK outside anti-money-laundering and financial promotion rules, a gap the FCA itself flags in its own notes to editors. That changes in two stages: firms could start applying for full authorisation from 30 September 2026, but the mandatory regime covering trading platforms, custodians and staking firms doesn’t actually bite until 25 October 2027. Until then, enforcement under the existing 2017 Money Laundering Regulations — like this September’s raids — is the main tool the FCA has, and it’s clearly willing to use it repeatedly rather than wait for the new rulebook.
What this means if you buy or sell crypto
This is reporting, not financial advice, but the FCA’s own guidance is worth repeating plainly: before you trade with anyone describing themselves as a crypto buyer or seller outside a recognised exchange, you can check whether a firm is genuinely FCA-registered using the regulator’s free Firm Checker. If a deal only works in cash, with no paper trail and no registration to check, that absence is itself the warning sign — and if something goes wrong, there is no registered firm, and no Financial Ombudsman route, to fall back on.
Sources
- FCA: “FCA and partners continues crackdown on illegal crypto trading” (published 17/09/2026, updated 01/10/2026)
- FCA: “FCA leads first crackdown on illegal crypto trading” (April 2026 operation)
- FCA: crypto ATM crackdown press release (34 locations inspected, 26 machines disrupted, 2023)
- GENERAL BYTES: “UK Crypto ATMs: A High-Risk Zone for Operators” (80 → 0 legal machines, last updated March 2026)
- FCA Firm Checker



Be First to Comment